Are you ready to become a homeowner?
We specialized in first-time homebuyers, second homes, investments, and other loan products. My two decades of experience will ease your worries. Inquire about the most competitive home loan programs in Texas that we can offer.
For Questions, Kindly fill-out the "Q&A with Broker"
form
Ready to apply? Click "Apply Now" to start the process

Because It’s Time To Seek Financial Assistance From an Expert
Down-payment Assistance
Inquire now for the assistance program
Fixed-rate Loans
Fixed-rate conventional mortgages
Specialty Loans
ITIN, Non-QM Loans
Hablamos Español
De nemos expertas que su idioma
Whatever the case may be, it's best that you inquire and talk to me. Let's see how I can help you and explore your options.
What are the Common Loan Programs?
Inquire for the most competitive loan options that you can get.

FHA Home Loan
FHA home loans are mortgages which are insured by the Federal Housing Administration (FHA), allowing borrowers to get low mortgage rates with a minimal down payment.

VA Loans
The VA Loan provides veterans with a federally guaranteed home loan which requires no down payment. This program was designed to provide housing and assistance for veterans and their families.

USDA Loans
If you're looking to buy a home in a rural or suburban area with no down payment and minimal investment, you might consider the USDA Rural Development Loan.

Jumbo Loans
Jumbo Loans are used to finance properties that are too expensive for a conventional conforming loan. There's maximum amount for a conforming loan as determined by the Federal Housing Finance Agency (FHFA).
With me, there's no compromise.
2 Decades of experience
As an experienced loan officer in Texas, you can count on me to guide you through the mortgage process. Whether you are a first-time homebuyer, a current homeowner wanting to refinance an existing mortgage or add an investment property to your rental portfolio, my focus is on providing a five-star customer experience. Texans Mortgage Group offers competitive interest rates and a wide range of loan products from fixed-rate conventional mortgages to FHA, VA, Jumbo loans as well as down-payment assistance programs.
NMLS# 262973 Co. NMLS # 2716207
No-hassle loan applications
Step-by-step guide in closing your loans
Home buying journey in 5 simple steps!
01: Find Out How Much you can Borrow
The first step in obtaining a loan is to determine how much money you can borrow. In case of buying a home, you should determine how much home you can afford even before you begin looking. By answering a few simple questions, we will calculate your buying power, based on standard lender guidelines.
02
: Select the right loan program
Home loans come in many shapes and sizes. Deciding which loan makes the most sense for your financial situation and goals means understanding the benefits of each.
03
: Apply for a loan
After figuring out which loans is the most beneficial for you. You can go ahead and start the application process.
04
: Begin loan processing
Although lenders conform to standards set by government agencies, loan approval guidelines vary depending on the terms of each loan.
05
: Close your loan
After your loan is approved, you are ready to sign the final loan documents. You must review the documents prior to signing and make sure that the interest rate and loan terms are what you were promised.

No Compromise, Just Maximize
Read our guides and more -- check out our blogs!
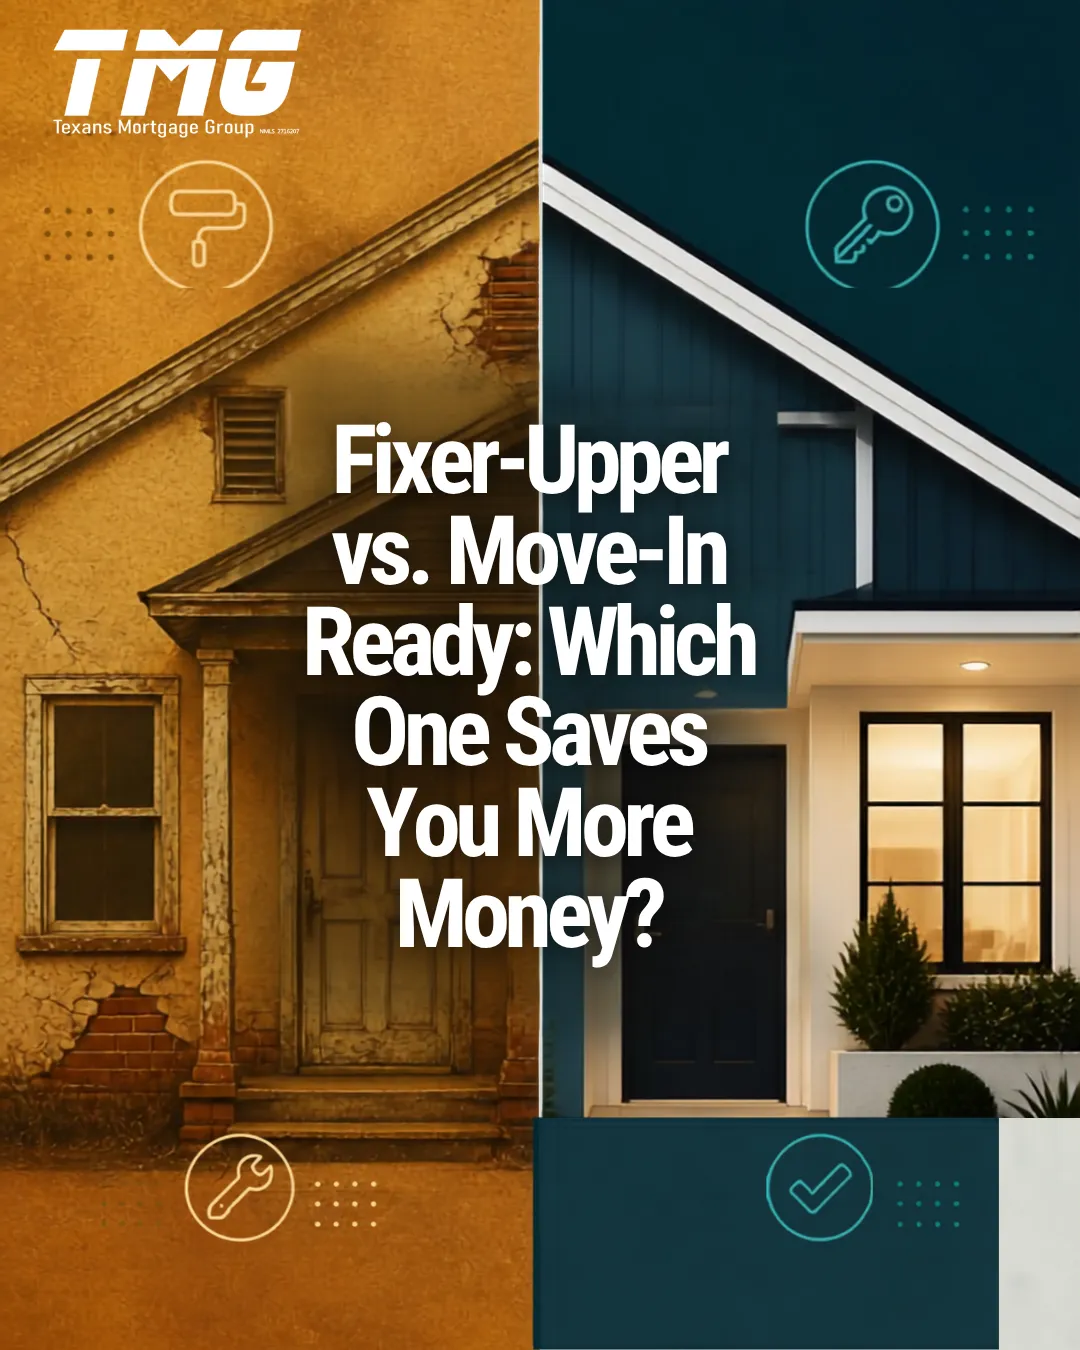
Fixer-Upper vs. Move-In Ready: Which One Saves You More Money?
“Beware of little expenses; a small leak will sink a great ship.”
- Benjamin Franklin
Buying a home is one of the biggest financial decisions you'll ever make. But when it comes to choosing between a fixer-upper and a move-in-ready property, the lowest asking price doesn't always mean the biggest savings.
Imagine finding two homes in your dream neighborhood. One is priced significantly lower but needs a new roof, updated plumbing, and a fresh coat of paint. The other costs more but is ready for you to move in as soon as you get the keys.
Which one is the smarter financial choice?
The answer depends on more than the purchase price. Your budget, renovation costs, financing options, and long-term plans all play a role in determining which home offers the best value.
Let's break down the differences.
1. The Appeal of a Fixer-Upper: Lower Price, More Potential
A fixer-upper is a property that needs repairs, renovations, or upgrades before it reaches its full potential. These homes often attract buyers because they may have lower asking prices than comparable move-in-ready properties.
Why a Fixer-Upper Could Save You Money
A lower purchase price. A fixer-upper may allow you to enter a desirable neighborhood at a lower price point, depending on the property's condition and local market.
The opportunity to build equity. If you purchase the property at a favorable price and complete cost-effective improvements, you may increase its market value. However, renovations do not guarantee a profit, and the results depend on market conditions and the quality of the work.
The freedom to customize. You can renovate the home to fit your preferences, from updating the kitchen to redesigning the bathroom. You may also choose which projects to complete first based on your budget.
The Hidden Costs to Watch Out For
The biggest mistake buyers make is underestimating renovation expenses.
A home that looks like it only needs cosmetic updates could have underlying problems, including:
Roof damage or leaks
Outdated electrical wiring
Plumbing issues
Foundation problems
Water damage or mold
Heating and cooling system repairs
These issues can quickly turn an affordable property into an expensive project.
Smart buyer tip: Before purchasing a fixer-upper, schedule a professional home inspection. Consider additional inspections for major systems or structural concerns when recommended. Knowing what needs attention can help you estimate the true cost of ownership before committing.
2. Move-In Ready: Pay More Upfront, Worry Less About Repairs
A move-in-ready home is generally in a condition that allows you to occupy it without needing major immediate renovations. It may still need minor maintenance or future updates, but significant repairs are less likely to be necessary right away.
Why a Move-In-Ready Home Could Save You Money
Fewer immediate expenses. You may avoid the need to spend thousands of dollars on urgent repairs or renovations immediately after closing.
More predictable budgeting. Without a long renovation list, you can focus on your mortgage, utilities, insurance, property taxes, and regular maintenance.
Less time and stress. You won't have to coordinate contractors, compare renovation quotes, or manage construction projects while trying to settle into your new home.
Potentially fewer surprises. A well-maintained home can make it easier to plan your finances, although even move-in-ready properties can have hidden defects.
What Should You Consider?
Move-in-ready homes often command higher asking prices, depending on the neighborhood, property condition, and current market demand.
You may also pay a premium for modern finishes, updated kitchens, new appliances, or other improvements that previous owners have already completed.
The key question is whether that higher price is justified by the home's condition, location, and overall value.
3. Let's Compare the Numbers
Sometimes, the easiest way to understand the difference is to look at a hypothetical example.
Suppose you're considering two homes in the same general area.
Expense | Fixer-Upper | Move-In Ready |
|---|---|---|
Purchase Price | $200,000 | $240,000 |
Estimated Renovation Costs | $25,000 | $0 in immediate major renovations |
Additional Repair Budget | $5,000 | $0 in immediate major renovations |
Estimated Total Before Closing Costs and Other Expenses | $230,000 | $240,000 |
Note: These figures are illustrative examples, not actual market prices or contractor estimates. The comparison excludes closing costs, financing expenses, taxes, insurance, ongoing maintenance, and other ownership costs. The move-in-ready home may still require repairs or maintenance.
In this example, the fixer-upper costs approximately $10,000 less before closing costs and other expenses.
That sounds like a clear win for the fixer-upper, right?
Not necessarily.
If the renovation costs increase by $15,000 because of unexpected problems, the fixer-upper's estimated total rises to $245,000. Suddenly, the move-in-ready home may be the less expensive option.
And there's another factor to consider: time.
If renovations take several months, you may need to pay for temporary housing, storage, or other additional expenses. Those costs can reduce or eliminate your expected savings.
The bottom line: Compare the total estimated cost of buying and preparing each home, not just the asking price.
4. Don't Forget the Cost of Financing
Your mortgage can also affect which option makes the most financial sense.
A lower-priced fixer-upper may require less money to purchase, but renovation expenses can create an additional financial burden.
Depending on the property and your loan program, you may need to explore financing options that account for both the purchase and eligible renovation costs. These programs have specific requirements, so speak with a qualified mortgage professional before assuming you can finance the repairs.
For a move-in-ready home, the higher purchase price may mean a larger mortgage and potentially higher monthly payments.
When comparing your options, consider:
Your down payment
Estimated monthly mortgage payments
Interest rate and loan terms
Closing costs
Available renovation financing
Cash reserves remaining after closing
Remember, using all your available savings to purchase a home can leave you financially vulnerable when unexpected expenses arise.
Choose an option that allows you to maintain a reasonable emergency fund after moving in.
5. Which Option Is Better for Your Financial Situation?
The right choice depends on your circumstances, priorities, and willingness to take on additional work.
A Fixer-Upper May Be Right for You If:
You have savings available for repairs and unexpected expenses.
You're comfortable managing renovation projects.
You have the time to oversee contractors or complete some improvements yourself.
You've researched local property values and understand the home's potential.
The purchase price and realistic renovation budget leave you with an attractive overall cost.
A Move-In-Ready Home May Be Right for You If:
You want to move in without major renovation delays.
You prefer predictable expenses.
You have limited time to manage contractors and repairs.
You don't want to take on the financial uncertainty of a major renovation.
You find a property whose price is reasonable relative to its condition and comparable homes.
Neither option is automatically better. The goal is to find a home that fits both your lifestyle and your financial situation.
6. Five Smart Tips Before Making Your Decision
Before choosing between a fixer-upper and a move-in-ready home, take these steps:
1. Get a professional home inspection. Understand the property's condition before committing to the purchase.
2. Request realistic renovation estimates. Speak with qualified contractors and compare written estimates instead of relying on guesses.
3. Set aside a contingency fund. Renovation costs can increase when contractors uncover unexpected problems. Your contingency should reflect the property's condition and the scope of the work.
4. Compare similar properties. Look at recently sold homes in the same area to understand whether the asking price reflects the property's condition and local market value.
5. Think beyond the purchase. Consider monthly payments, utilities, insurance, property taxes, maintenance, and how much cash you'll have left after closing.
Taking these steps can help you avoid costly surprises and make a more confident decision.
So, Which One Actually Saves You More Money?
The truth is that neither a fixer-upper nor a move-in-ready home guarantees greater savings.
A fixer-upper may offer a lower total cost if you purchase wisely, accurately estimate repairs, and manage renovations within budget.
A move-in-ready home may offer better value if the higher purchase price is offset by fewer immediate repairs, less renovation spending, and a more predictable move-in process.
The smartest purchase isn't necessarily the cheapest house. It's the one that delivers the best overall value without putting your financial stability at risk.
Before making an offer, compare the complete cost of each option, understand the risks, and make sure the home supports your long-term goals.
Because when it comes to buying a home, a little preparation today can help you avoid expensive surprises tomorrow.
Thinking About Buying a Home?
Whether you're considering a fixer-upper or a move-in-ready property, having the right information can make all the difference.
Take the time to evaluate your options, ask questions, and understand the numbers before making a decision.
Your future home should be an investment in your life, not a source of unnecessary financial stress.
Disclaimer: This content is intended for general information purposes and not as personalized financial advice. For tailored guidance, consult with the experts at Texans Mortgage Group.
Aliquam Venenatis, Sapien
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Duis imperdiet nisi ac augue element
Aliquam Venenatis, Sapien
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Duis imperdiet nisi ac augue element
Aliquam Venenatis, Sapien
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Duis imperdiet nisi ac augue element
Aliquam Venenatis, Sapien
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Duis imperdiet nisi ac augue element
Hear What Our Clients Say
Reviews were imported from Google & Facebook
Edwin Armilla
Mr. Zarate was very helpful through the whole lending process. Any questions I had were always answered in a timely manner. Very knowledgeable and great communication. Definitely would recommend to anyone.
Elaine Carrasco
As a Realtor, I give Rudy Zarate 5 stars. He always answered his phone and he provided top notch service, always providing updates for my buyers and myself, every step of the way. He certainly went the extra mile! Thank you, looking forward to doing business again soon!!
Steven Doran
Rudy is the man, he got it done! I have less than stellar credit and he made my dreams of home ownership a reality. We first talked in the summer and he gave me the right pointers to improve my credit to qualify for a loan. Today a few months later I just closed on my new home.
Rudy and team are amazing, and they are excellent at communicating and keeping you informed along the way. Communication is key when you’re doing something as big as applying for a mortgage, and Rudy has by far been the best mortgage broker I’ve had the pleasure of dealing with. I will definitely recommend him and use him again in the future if the opportunity arises.
Fernanda Alvarado
Rudy and his team helped me out so much!! Im so thankful for law firm Jackeline Gonzalez for recommending me to Texans Mortgage. Everything has been so smooth!!

Address: 910 Fairmont Pkwy. #145, Pasadena, TX 77504
COMPANY NMLS: 2716207
RUDY ZARATE | NMLS #262973 | Texans Mortgage Goals LLC | NMLS #2716207
This is not a commitment to lend. All loans are subject to credit approval.
All Rights Reserved.
tmg@rudyzarate.com
Our Houston, TX Office:
(281) 747-6699
Operating Hours:
Mon 08:30 am – 05:30 pm
Tue 08:30 am – 05:30 pm
Wed 08:30 am – 05:30 pm
Thu 08:30 am – 05:30 pm
Fri 08:00 am – 05:00 pm
Weekends Closed